

Karl has been involved in the business to business information service since 1990. Having spent time with information to the construction and manufacturing industry in the UK, Sweden, Switzerland, Germany and the US.

Machining
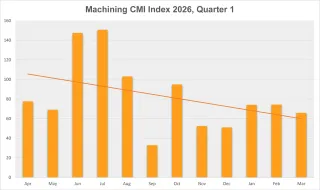
The machining sector recorded an index of 71. This represented a 26% decrease from the previous quarter, but a 69% increase year-on-year. Machining contributed a total outsourcing value of £43 million during the quarter.
Fabrication
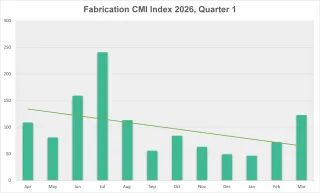
Fabrication was the strongest performing category this quarter, achieving an index score of 80. Although this was a 42% drop from the previous quarter, it remained a massive 90% higher than the same period 12 months prior. Fabrication projects accounted for the highest outsourcing value this quarter, totalling £45.4 million.
Others
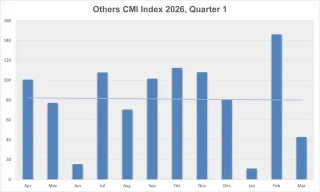
Processes falling outside of core machining and fabrication achieved an index of 67. This was 28% lower than the previous quarter, but 46% higher than the previous year, generating an outsourcing value of £7.7 million.
Industry
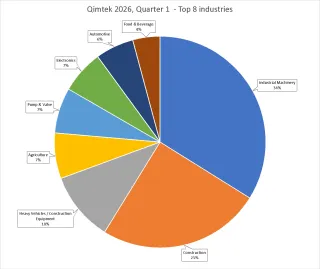
Major Growth: Industrial Machinery took over as the dominant sector, growing from 22% to 34%, while Construction surged from 7% to 25%.
Steep Decline: The Automotive sector, which previously led the market, plummeted from 31% down to just 6%.
Stable Sectors: Heavy Vehicles/Construction Equipment (~10-11%) and Food & Beverage (~4-5%) remained relatively unchanged.
New Entries: Agriculture, Pump & Valve, and Electronics (all at 7%) entered the top 8 in Q1 2026, replacing Consumer Products, Marine, and Truck & Transportation, which fell off the list.
About Contract Manufacturing Index
The Contract Manufacturing Index (CMI) has been developed to reflect the total purchasing budget of companies that are looking to outsource subcontract manufacturing of custom made parts in any given month.
This reflects a sample of over 4,000 companies, who have a purchasing budget of more than £5bn and a supplier base sample of over 7,000 vendors, with a verified turnover in excess of £25bn.
We measure this by extracting data from the projects we receive from manufacturing purchasers who have an active need for the services of subcontract engineering suppliers.
Since 2016, we have published the index quarterly and this report is a summary of our findings for the this current quarter. In order to shed more light on the emerging trends, we have also broken this down by process and industry.